After years of H-1B renewals, priority date discussions, immigration paperwork, and waiting, receiving a green card feels like the finish line.
For many Indian professionals, it's one of the biggest milestones of their lives.
What often gets overlooked is that the green card doesn't just change your immigration status. It changes your tax status too.
The day you become a lawful permanent resident, the IRS starts looking at your finances differently. Bank accounts in India, mutual funds purchased years ago, provident funds, rental properties, and investment income that may never have appeared on your US tax return before can suddenly become part of your reporting obligations.
The challenge is that most people don't learn about these rules when they receive their green card. They discover them later, often after missing important disclosures or filing requirements.
Here's what changes and what every Indian professional should understand during their first year as a green card holder.
The Tax Status Shift
Many Indians working in the US on H-1B visas already file taxes as resident aliens under the Substantial Presence Test.
But that determination is reviewed every year based on time spent in the United States.
A green card changes the equation.
From the date your green card is issued, you are generally considered a US person for tax purposes until you formally give up permanent residency or your status changes.
That means the IRS expects you to report your worldwide income. Not just your US salary.
This can include:
- Rental income from property in India
- Interest earned on NRE and NRO accounts
- Dividends from Indian investments
- Foreign business interests
- Capital gains from overseas assets
For many Indian professionals, the first full-year tax return after receiving a green card is the most complex return they will ever file.
FBAR: What Needs to Be Reported and What the Threshold Actually Means
One of the biggest surprises for new green card holders is the FBAR requirement.
The rule sounds simple, but it's often misunderstood.
If the combined maximum value of all your foreign financial accounts exceeds $10,000 at any point during the year, you may need to file FinCEN Form 114, commonly known as the FBAR.
The important word here is combined. Many people assume the threshold applies to each account individually. It doesn't.
A few common accounts that may be reportable include NRE accounts, NRO accounts, savings accounts, fixed deposits, demat accounts, mutual fund accounts, EPF accounts, PPF accounts, and NPS accounts.
Joint accounts create confusion as well. In many situations, each account holder reports the full account value.
Even signing authority can trigger reporting. If you have authority over a parent's account, that account may need to be disclosed even if the money doesn't belong to you.
The filing deadline is April 15, with an automatic extension available through October 15.
FATCA: Form 8938 and How It Differs From FBAR
A common misconception is that once you've filed an FBAR, you're done.
In reality, another reporting requirement may apply.
Form 8938, filed under FATCA rules, is attached to your federal tax return and covers certain foreign financial assets.
Unlike the FBAR, which focuses on foreign accounts, Form 8938 can also include Indian mutual funds, stocks held through demat accounts, interests in foreign businesses, and other specified foreign investments.
The reporting thresholds are generally higher than FBAR thresholds. For taxpayers living in the United States, reporting often begins at $50,000 for single filers and $100,000 for married couples filing jointly.
The important thing to understand is that FBAR and Form 8938 are not substitutes for each other. In many cases, the same asset may need to appear on both filings.
Indian Mutual Funds Are PFICs, and the Default Tax Treatment Is Punitive
This is where many green card holders run into problems.
In India, mutual funds are one of the most common investment vehicles. In the United States, they're often treated very differently.
Most Indian mutual funds are classified as Passive Foreign Investment Companies, or PFICs. This includes equity funds, debt funds, hybrid funds, and many ULIP-based investments.
The default PFIC tax rules can produce surprisingly harsh results. In some cases, gains and distributions are taxed under a special regime that may result in higher taxes and additional interest charges.
What makes this particularly important is timing. A mutual fund purchased years before receiving a green card can still create reporting and tax complications after becoming a permanent resident.
For many Indian professionals, PFIC reporting becomes one of the most important parts of their first green card tax return and one of the most commonly overlooked.
NRE Account Interest: The Most Commonly Misfiled Item
One of the most frequent mistakes we see involves NRE account interest.
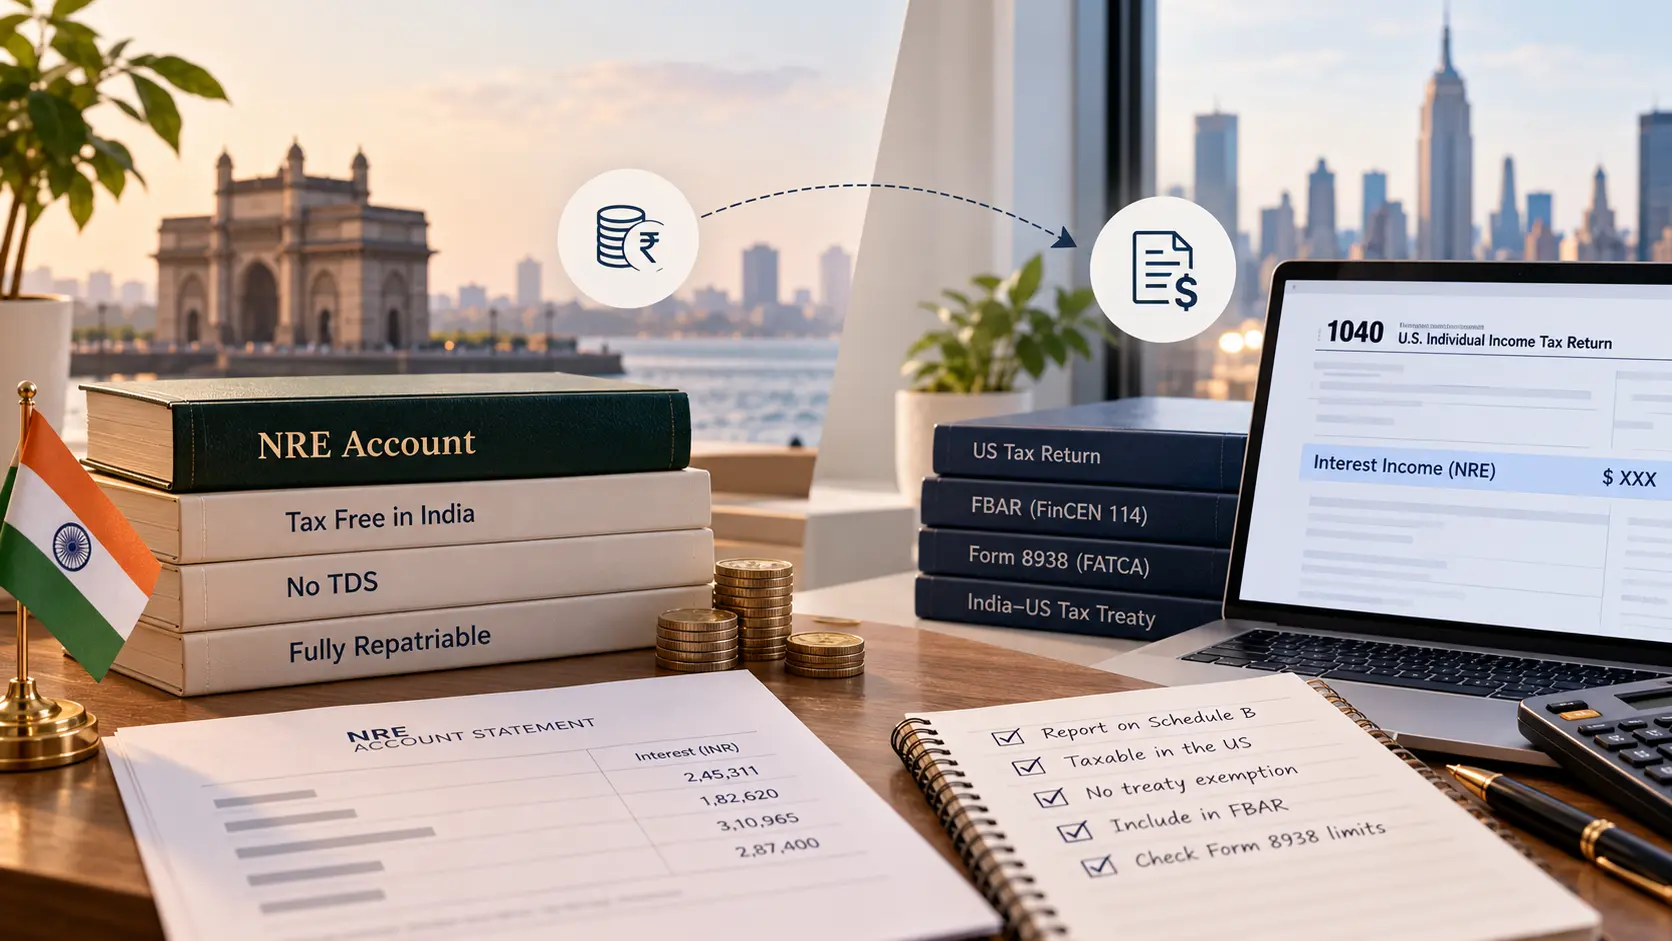
Because the interest is tax-free in India, many assume it remains tax-free after they receive a green card. It doesn't.
The IRS generally treats NRE account interest as taxable interest income that must be reported on your federal return. The India-US tax treaty does not provide an exemption for this income.
Unfortunately, this misunderstanding often continues for years because taxpayers rely on Indian tax treatment without realizing the US rules are different.
Indian Provident Funds: EPF, PPF, NPS
Provident fund accounts create another layer of complexity.
Many green card holders assume these accounts don't require attention because they're retirement-focused and may not be accessible immediately. The IRS doesn't necessarily view them that way.
EPF, PPF, and NPS each have different tax considerations, but all deserve careful review. Questions often arise around annual earnings, employer contributions, reporting requirements, future withdrawals, and FBAR disclosures.
These accounts can become particularly important when balances grow over time and reporting obligations are overlooked.
The 8-Year Exit Tax Clock
Most people spend years trying to get a green card. Very few think about what happens if they decide to give it up later.
But the clock starts ticking on day one.
Under US tax rules, certain long-term residents who have held a green card for at least 8 of the previous 15 years may become subject to expatriation tax rules if they abandon permanent residency.
Often called the exit tax, these rules can treat assets as though they were sold immediately before expatriation.
For professionals with significant investments, this can become an important long-term planning issue. The key point is simple: the 8-year clock starts when the green card is issued, not when you begin considering a move back to India.
Conclusion
Getting a green card is a significant achievement, but it also introduces tax obligations that many Indian professionals don't discover until years later.
Worldwide income reporting, FBAR filings, FATCA disclosures, PFIC rules, provident fund reporting, and future exit tax considerations can all become part of your tax life almost immediately.
The first tax return after becoming a permanent resident often sets the foundation for everything that follows. Getting it right early can help avoid years of corrections, missed filings, and unnecessary stress.
At GoalSeek, we help US-based NRIs and Indian professionals navigate first-year green card tax returns, FBAR and FATCA reporting, and ongoing cross-border compliance so they can stay focused on their financial goals while remaining fully compliant on both sides of the border.