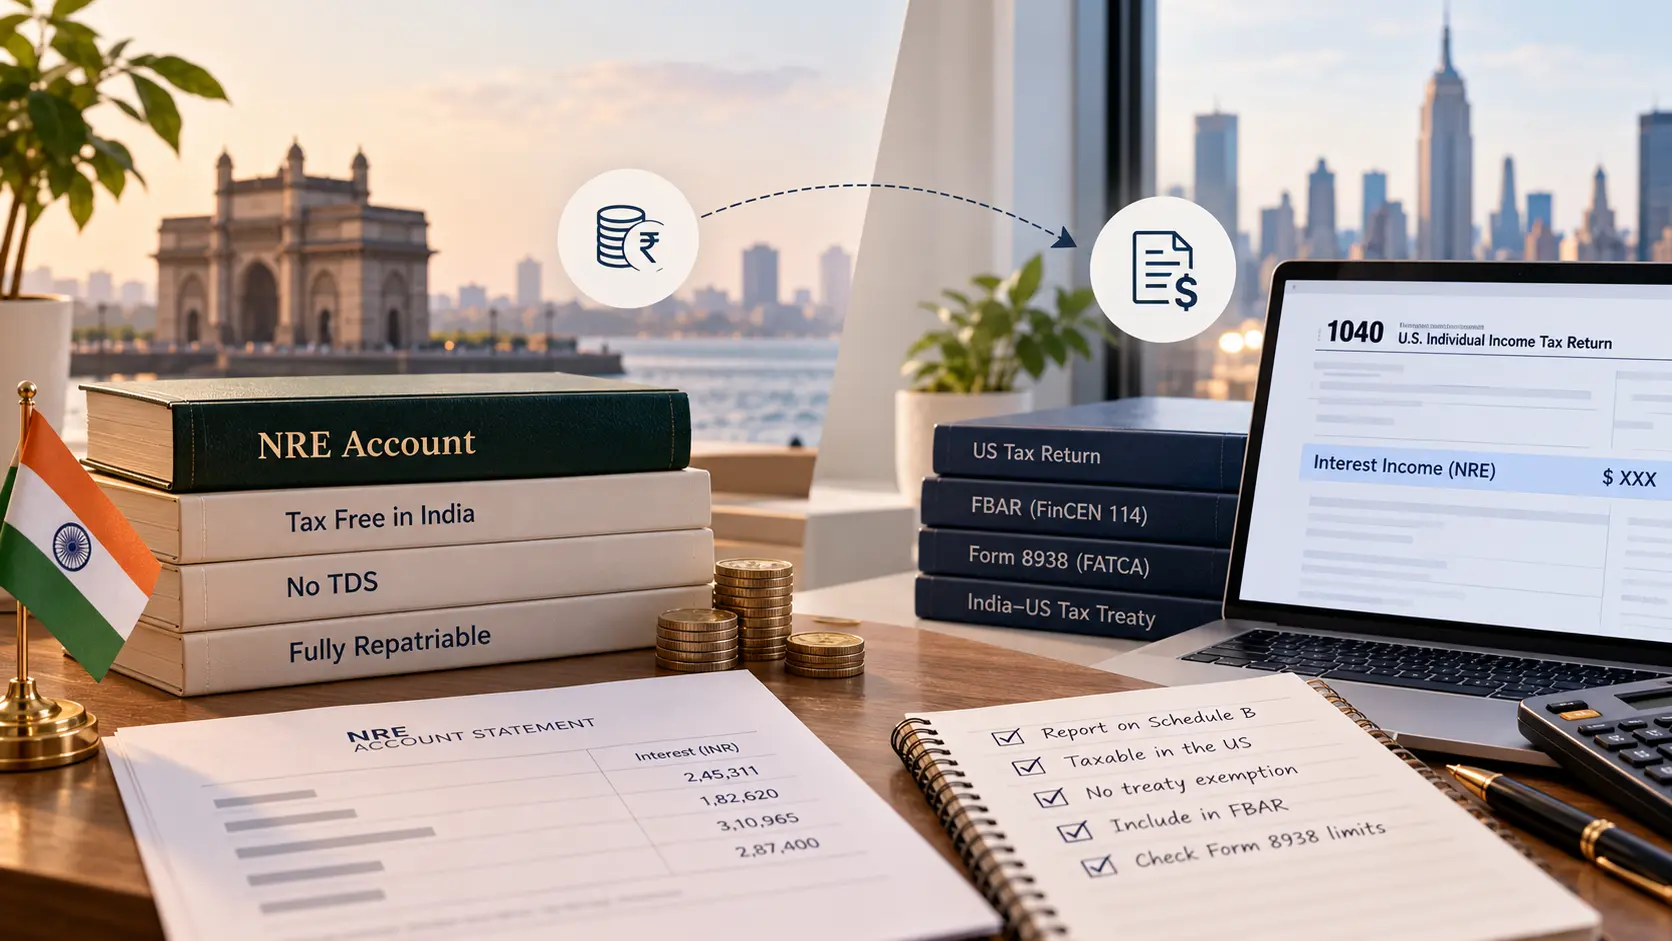
NRE account interest is one of the most misunderstood parts of NRI taxation. In India, the treatment is simple: interest earned in an NRE account is fully tax-exempt. No TDS. No reporting. No tax. That is correct under Indian law.
But many US-based NRIs assume this exemption continues on their US tax return. It does not. The IRS treats NRE account interest as fully taxable ordinary income. It must be reported, taxed at the filer's marginal rate, and included in annual income even if no tax is paid in India. The India-US tax treaty does not override this treatment.
NRE vs NRO Accounts: Why the Difference Matters
An NRE account holds foreign income converted into INR, has fully repatriable principal and interest, and pays interest that's tax-free in India with no TDS deducted. From a US perspective, this creates a simple but important outcome: there is no foreign tax paid, so there is no foreign tax credit available. The full interest is taxable in the US.
An NRO account holds income earned in India, is subject to 30% TDS in India (reduced to 15% under DTAA), and is eligible for Foreign Tax Credit in the US via Form 1116. So while NRO interest may reduce US tax through credits, NRE interest does not. Both accounts must be reported on FBAR if aggregate foreign balances cross $10,000 at any point during the year.
Why the Tax Treaty Does Not Protect NRE Interest
A common misunderstanding is that the India-US DTAA exempts NRE interest. It does not. The reason is the saving clause in Article 1 of the treaty, which allows the United States to tax its citizens and residents as if the treaty did not exist in most cases. So even though India does not tax NRE interest, the US still does. Article 11 of the treaty governs interest income, but it only limits Indian taxation on certain types of interest; it does not create an exemption in the US.
The correct US treatment: report NRE interest on Schedule B of Form 1040, no treaty exemption claimed, no foreign tax credit applied, fully taxable as ordinary income.
FBAR Reporting: The Rule That Gets Missed Most Often
FBAR (FinCEN Form 114) is separate from your tax return. It applies when the total value of foreign financial accounts exceeds $10,000 at any point in the year, not at year-end. Accounts that must be reported include NRE and NRO accounts, fixed deposits, savings accounts, EPF and PPF accounts, demat accounts, mutual fund holdings, and insurance policies with surrender value.
Two key rules people often miss: joint accounts require each US person to report the full value, not just their share; and signing authority over a parent's account still requires reporting even if the money isn't yours.
Post-2023 Bittner ruling, penalties for non-willful violations are generally assessed per form, not per account. For 2026, that is approximately $16,536 per FBAR violation, significantly lower than the older per-account interpretation. Willful violations remain far more severe and can reach 50% of account balances per year.
Form 8938: The Second Layer Most People Miss
Form 8938 is filed with your tax return under FATCA rules. It applies when foreign asset thresholds are met: $50,000 at year-end or $75,000 at any point for single filers, $100,000 or $150,000 for joint filers. Unlike FBAR, Form 8938 covers more than bank accounts, including Indian mutual funds, demat holdings, ownership in Indian businesses, and certain insurance and pension assets. Both FBAR and Form 8938 can apply at the same time; filing one does not replace the other.
When Things Go Wrong: Fixing Past Non-Compliance
A common situation: an NRI has been filing US tax returns for years but never reported NRE interest or FBARs. The IRS provides correction pathways. The Streamlined Domestic Offshore Procedures (for US residents) require 3 years of amended returns, 6 years of FBARs, and tax due plus a 5% penalty on the highest account balance. The Streamlined Foreign Offshore Procedures (for NRIs outside the US) require the same filings with no 5% penalty, but require certification of non-willful conduct. The Delinquent FBAR Procedure applies when income was properly reported but FBAR was missed, generally with no penalty if no tax was avoided. The key condition for all of these programs is timing: once the IRS begins an audit or contacts the taxpayer, these options may no longer be available.
Conclusion
NRE account interest is not a grey area in US tax law. It is taxable, reportable, and often missed because Indian tax treatment gets incorrectly assumed to apply in the US. For NRIs, the issue is rarely intent. It's information mismatch between two tax systems. Correction is possible, and structured pathways exist to fix past filings, but waiting for the IRS to identify the issue is where the cost increases significantly.
At GoalSeek, we help US-based NRIs with cross-border tax compliance, including FBAR filings, Form 8938 reporting, and accurate treatment of NRE and NRO income on US returns.